

Ualett
Cabicash Solutions, Inc
- 4.6
- 1.28K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
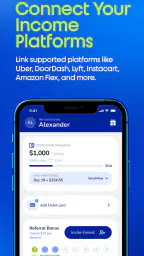
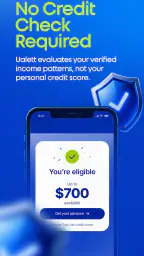
Ualett Pros and Cons
Pros
- Fast access to earned wages without waiting for payday.
- Simple mobile application with an easy-to-follow cash advance process.
- Transparent repayment schedule shown before accepting an advance.
- Useful for covering unexpected bills or short-term financial gaps.
- Funds can be requested without relying on traditional bank loans.
Cons
- Eligibility and advance limits may vary based on account activity.
- Fees can make repeated advances expensive over time.
- Repayment is typically automatic, requiring careful budget planning.
- Not available to all workers, employers, or geographic locations.
- Late or failed repayments may affect future access to advances.
 Analysis by All-app
For people who earn money through flexible work, the difficult part is often not finding a shift or completing a delivery; it is managing the uneven timing of income afterward. Ualett is a free finance app built around that reality. I found its focus much narrower than a general banking app, and that is its main appeal: it is aimed at gig workers who need a more practical way to think about money arriving from irregular work.
The app comes from Cabicash Solutions, Inc., and its store summary describes it as built for gig workers. That short positioning tells you more than a broad “personal finance” label would. This is not the kind of app I would choose simply to track household spending, compare investment products, or replace every financial tool on my phone. I see it as a focused companion for someone whose working week changes constantly and who wants financial tasks organized around that pattern.
My overall impression is positive, but with an important qualification: Ualett makes the most sense when your financial life is closely connected to gig work. If you have a regular salary, already use a full-service bank, or want detailed budgeting and long-term planning, a conventional banking or budgeting app may suit you better. If your income depends on several short jobs, however, the focused design can feel more relevant than a general-purpose alternative.
How Ualett feels during everyday financial work
I look at trust in a finance app as a practical question: what choices can I see, and what can I verify before relying on it? In this section, I focus on how Ualett fits into a careful workday routine, including the moments when I would pause to check an account or confirm an action. That perspective leads naturally to a closer look at the controls a user can actually assess.
Speed expectations when time matters
The first thing I pay attention to in a finance app is whether it gets out of the way. When I am checking money between jobs, I do not want a crowded dashboard or a long learning process. Ualett’s appeal is that its purpose is easy to understand from the start: it is intended for people earning through gig work. That clear audience can make the initial experience feel more direct than an app designed for everyone from students to investors.
Still, “fast” should be understood carefully here. An app can open quickly and present information clearly, but financial actions may still depend on account checks, network conditions, and the services connected to the transaction. I would not treat a smooth screen transition as a promise that every money movement will be immediate. For urgent expenses, I would check the status of an action before assuming the funds are ready to use.
My practical advice is to set up and explore Ualett before you are standing at a fuel station or finishing a late delivery. Testing the main screens during a calm moment lets you learn where to look when you are tired. It also gives you a chance to notice whether your phone, connection, and account details are ready for the actions you expect to perform.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
A useful workflow is to separate “checking” from “acting.” First open the app and confirm the current state of your finances. Then decide whether you actually need to move or use money. This small pause matters for gig workers because earnings can arrive at different times, and a balance that looks available may already be mentally assigned to fuel, food, rent, or another obligation.
What happens during heavy-use moments
The most demanding situation is not necessarily opening the app once. It is using it repeatedly across a long working day: checking before accepting a job, checking again after completing it, and returning later when a bill is due. That pattern is common for drivers, couriers, freelancers, and other workers whose income and expenses move together.
In that kind of routine, I value a finance app that keeps the essential information easy to find. Ualett’s gig-worker focus gives it a sensible place in this workflow. Instead of forcing you to translate a traditional banking layout into your working life, the app is presented around the needs of people with nontraditional income. That does not remove every financial decision, but it can reduce the mental effort involved in making those decisions.
There is also a trade-off. A focused app may be easier for one job-related purpose while offering less depth than a complete banking suite. If you want extensive spending categories, detailed reports, savings goals, credit products, or investment management in the same place, you may end up switching between Ualett and another service. I consider that acceptable when the app handles the gig-work part well, but it is worth planning for before making it your only financial tool.
Here is the everyday scenario where I think it can be most useful. Imagine finishing several delivery blocks and needing to decide whether today’s earnings can cover tomorrow’s fuel and a scheduled payment. I would use Ualett to review the money connected to my work routine, keep the immediate decision separate from longer-term budgeting, and then use a second tool if I needed a broader household overview. That division of labor is more realistic than expecting one app to solve every financial problem.
For heavy use, I also recommend avoiding unnecessary background activity when your phone battery is already low. Finance apps do not need to be open continuously for most people, and gig work often keeps the phone busy with navigation, calls, and work platforms. Opening Ualett when needed rather than leaving several apps active can make the whole device feel less strained, especially on an older handset.
Reliability, recovery, and sensible habits
Reliability in finance is more than an attractive interface. I want confidence that I can return to the app, understand what happened, and recover from an interrupted session. A weak connection, a closed screen, or a phone that switches networks should not leave me guessing about whether an action completed.
Because of that, I would treat confirmation screens and transaction status as essential, not optional. After any important action, I would remain in the app long enough to verify the result and keep a personal note if the money is needed for a time-sensitive bill. This is not a criticism unique to Ualett; it is a sensible habit with any financial service. The cost of assuming something succeeded can be much higher than the few seconds spent checking.
If Ualett appears slow or fails to load, I would work through recovery in a calm order: check the connection, close and reopen the app, and try again when the network is stable. I would avoid repeatedly submitting the same financial request simply because the first screen took time to respond. When an action involves money, duplication is a bigger risk than waiting.
I also prefer keeping the app updated rather than postponing every update indefinitely. Ualett’s current version is 2.73.0, so users who install it should pay attention to the version shown on their device and keep their operating system compatible. Updates can be inconvenient during a working day, which is why I would handle them before a busy shift rather than at the moment I need access.
The app has a 4.6 average from around 7,600 ratings, with roughly 1,300 written reviews. That level of public response suggests that many users find value in the service, but I would not read a rating as a guarantee of identical results for everyone. Finance apps are especially sensitive to personal circumstances, account setup, device condition, and connection quality. I use the rating as a reason to investigate further, not as a substitute for testing the app myself.
Device constraints and the role of your phone
Ualett is available for Android devices running version 8.0 or later. That makes it accessible to people who do not own a recent flagship phone, which matters in gig work because a phone is often a work expense rather than a luxury. Someone using an older device may prefer to keep it in service instead of replacing it just to run a finance app.
At the same time, operating-system compatibility is only one part of the experience. A phone with limited free storage, a worn battery, or an unreliable mobile connection can make any financial app feel slow. Gig workers commonly use navigation, messaging, camera, work-platform, and payment apps in the same shift. The combined load may affect the phone more than Ualett alone.
I would prepare the device before relying on it. Remove apps you no longer use, leave enough storage for normal updates, and avoid starting a financial task while the phone is overheating or nearly out of battery. If you work in areas with inconsistent reception, plan important account checks for a place where the connection is stronger. These steps do not change Ualett’s features, but they can make the difference between a confident check and a stressful one.
The Everyone content rating is another reason the app can be considered broadly accessible. That rating describes the intended age suitability, not financial suitability. A younger user or a new gig worker may still need help understanding income planning, taxes, emergency savings, and payment timing. Ualett can support a financial routine, but it should not be mistaken for personal financial education or professional advice.
Where it fits beside ordinary alternatives
Compared with a standard banking app, Ualett’s strongest distinction is its audience. A normal bank application may be better if you need branches, a wide range of account services, extensive statements, or a complete view of household finances. Its menus are usually built around traditional banking relationships, which can be familiar and comprehensive.
Compared with a budgeting app, Ualett is likely to appeal more to someone who wants finance organized around gig work rather than detailed expense classification. Budgeting software is often stronger for monthly targets, category limits, and long-term planning. I would choose that route if my main question were, “Where did every part of my spending go?” I would look to Ualett when the more immediate question is, “How do I manage money connected to flexible work?”
Compared with a digital wallet, the choice depends on what you need most. A wallet is convenient for quick payments and storing payment methods, while a focused finance app can be more relevant when your concern is the broader handling of irregular earnings. I would not automatically replace one with the other. In my view, they can serve different moments of the same workday.
The practical trade-off is simplicity versus coverage. Ualett’s narrow purpose may help it feel less overwhelming, but a narrow purpose also means you may need another service for household budgets, savings, tax preparation, or long-term goals. That is not a deal-breaker. In fact, separating work-related money management from general banking can make your finances easier to understand, provided you keep track of both sides consistently.
Who should use it, and who should skip it
I would recommend trying Ualett if you earn through delivery work, driving, freelancing, or another flexible arrangement and want a finance app that recognizes that pattern. It is especially worth considering if traditional banking tools feel too general and you want a focused starting point rather than a large collection of unrelated features.
I would be more cautious if you need a single application for every financial task. Someone managing a family budget, several savings goals, investments, detailed tax records, and conventional payroll income may find a full banking or budgeting platform more efficient. Adding Ualett could create another place to check rather than simplifying the routine.
I would also skip making it your only financial backup. Keep access to your principal banking or payment service, know how to contact the relevant provider, and avoid storing your entire financial plan in one application. That is a sensible precaution for any finance tool, particularly when your ability to work depends on your phone.
Since the app is free, the barrier to trying it is low, but free does not mean cost-free in a wider sense. Your time, attention, data usage, and willingness to maintain another financial account all matter. I would install it only after deciding what specific gig-work problem I want it to solve. A clear purpose makes it easier to judge whether it is helping.
My performance verdict after looking at the full routine
Ualett is most convincing as a focused finance app for people whose income does not arrive in a neat monthly pattern. Its strongest quality is relevance: the gig-worker angle gives the app a reason to exist beyond simply copying a general bank dashboard. The free price and broad device support also make it approachable for workers who need to control expenses carefully.
My view of speed is cautiously favorable rather than absolute. The focused purpose should make everyday navigation easier to understand, but I would still allow for connection delays and account-processing time. My view of stability is similar: use it confidently as part of a routine, but confirm important actions and keep a backup way to manage urgent finances.
The app has been available since August 21, 2018, and its current version shows that it continues to be maintained as a live product. Its public reception is strong, with over 100,000 installs and a 4.6 average, but those figures should support—not replace—your own short trial. I would spend a few ordinary workdays learning whether the app fits my income pattern before depending on it for critical payments.
My bottom line is simple: Ualett is a sensible specialist tool, not a universal replacement for banking. If you are a gig worker who wants a finance experience shaped around irregular earnings, it deserves a place on your shortlist. If your needs are broader or more traditional, a bank or budgeting app may remain the better center of your financial life. Used with that distinction in mind, Ualett can make the money side of flexible work feel more manageable without pretending to solve every part of it.
Frequently Asked Questions
What is Ualett and what can I use it for?
Ualett is a digital financial service designed to help users manage everyday money tasks from a mobile device. Depending on the services available in your location, you may be able to receive payments, transfer funds, review transaction activity, and access other wallet or banking features. Before downloading, check the official listing to confirm which functions are currently supported in your country.
Is Ualett available for both Android and iPhone?
Ualett may be available for Android and iOS, but availability can depend on your country, device compatibility, and the version published in the relevant app store. Before installing, verify that the developer name is correct, read the latest requirements, and make sure your phone uses a supported operating system. Avoid downloading unofficial APK files from unknown websites.
What information is required to create a Ualett account?
Creating a Ualett account may require personal details such as your name, phone number, email address, and date of birth. Because financial applications often follow identity-verification rules, the app may also request an official identification document or additional information. Requirements can vary by region, so review the privacy policy and registration instructions before submitting sensitive data.
Is Ualett safe to use for financial transactions?
Ualett should be used only after confirming that you have downloaded the official application and are connecting through a secure internet connection. Protect your account with a strong, unique password or passcode, enable available security options, and never share verification codes. Also review fees, transaction limits, privacy practices, and customer-support details before keeping significant funds in the app.
Are there fees or limits when using Ualett?
Ualett may apply fees or limits depending on the transaction type, payment method, account status, and your location. Possible charges can include transfers, withdrawals, card-related services, currency conversion, or expedited processing. These conditions may change, so check the current fee schedule inside the app or on the official website before completing a transaction or relying on Ualett for regular payments.


